

“FTAsiaEconomy crypto trends” is a search phrase used to describe cryptocurrency and blockchain activity across Asia’s major financial markets. It is not tied to any single company or official publication. Key developments include Hong Kong’s new stablecoin licensing regime, Japan’s plan to cut crypto taxes from 55% to 20%, and Asia-Pacific posting a 69% increase in on-chain transaction volume in 2025. Stablecoin payments and real-world asset tokenization are the two fastest-growing areas right now.
Asia-Pacific just posted a 69% jump in crypto transaction volume in a single year. At the same time, China bans most private crypto activity, Japan is still taxing crypto gains at up to 55%, and Singapore is pulling back on some overseas crypto services. The same region is both the world’s fastest-growing crypto market and one of its most fragmented.
That mix of speed and contradiction is exactly what the phrase “FTAsiaEconomy crypto trends” points at. This article breaks down what the phrase means, which countries are driving the numbers, and which specific developments in 2025 and 2026 matter most.
What Does “FTAsiaEconomy Crypto Trends” Actually Mean?
“FTAsiaEconomy crypto trends” is a search label, not the name of an official company, report, or publication. There is no single verified organization behind the phrase.
People use it as shorthand for one broader question: what is happening with cryptocurrency and blockchain technology across Asia’s major financial economies? When you see the term used online, it almost always points to the same subject: how governments, banks, and everyday users in places like Hong Kong, Japan, Singapore, India, and China are handling digital assets right now.
That is the scope this article sticks to. The focus is on what is confirmed by research firms, regulators, and published data, not on projections or speculation.
Why Asia Leads Global Crypto Activity
Asia is not just participating in global crypto growth. It is driving most of it.
According to Chainalysis’s 2025 Global Crypto Adoption Index, the Asia-Pacific region grew its on-chain transaction volume from 1.4 trillion dollars to 2.36 trillion dollars in the 12 months ending June 2025. That is a 69% year-over-year increase, the fastest growth rate of any region in the world.
The Chainalysis report noted that this growth is not coming from speculation alone. In countries like Vietnam, the Philippines, Indonesia, and India, people use crypto primarily for remittances and cross-border payments. Stablecoin rails settle faster and cost less than traditional banking corridors. The Bank for International Settlements has observed that stablecoin use rises during periods of currency volatility in economies with high financial technology awareness. That pattern fits most of Southeast Asia well.
Which Countries Are Driving the Numbers?
- India: Ranked number one globally in Chainalysis’s 2025 adoption index for the second year in a row. Growth was boosted by regulatory momentum and increased participation from institutions.
- Singapore: Ranked number one in penetration rate among 2025 studies, with crypto ownership as high as 24.4% of the population depending on the measurement used. Six Asia-Pacific countries landed in the top 20 globally.
- Vietnam and Pakistan: Both rank in the top five globally for grassroots crypto activity. Usage is driven by peer-to-peer transactions, remittances, and decentralized finance access.
- Japan: Posted roughly 120% growth in on-chain received value during 2025, according to Chainalysis data, as regulatory reform began attracting more institutional participation.
How Are Asian Countries Regulating Crypto? A Country-by-Country Breakdown
Regulatory fragmentation is the defining feature of Asian crypto right now. No single framework covers the region. Each country is writing its own rules, and those rules sit far apart from each other.
| Country | Regulatory Stance | Key 2025-2026 Development | Crypto Friendliness |
| Hong Kong | Licensed and regulated | Stablecoins Ordinance in force since August 1, 2025; HSBC and Anchorpoint licensed April 2026 | High, institutional focus |
| Japan | Modernizing rapidly | FSA reclassifying 105 cryptos as financial products; flat 20% tax reform planned | Rising |
| Singapore | Regulated, selective | MAS restricting overseas crypto services since June 2025; CBDC consultation September 2026 | High for institutions |
| China | Heavily restricted | e-CNY expanding; eight-agency joint notice banned unapproved RMB-pegged stablecoins, February 2026 | Low for private crypto |
| India | Evolving | Tops global adoption; Chainalysis notes accelerating institutional participation | Growing |
| South Korea | Developing | Watching Hong Kong’s licensing model; accelerating its own stablecoin framework | Moderate |
Hong Kong’s Stablecoin Licensing Model
Hong Kong passed the Stablecoins Ordinance on May 21, 2025. The law took effect on August 1, 2025. It requires any entity issuing a fiat-referenced stablecoin in or from Hong Kong to obtain a license from the Hong Kong Monetary Authority, also known as the HKMA.
On April 10, 2026, the HKMA granted its first two stablecoin licenses. The recipients were HSBC and the Standard Chartered-led Anchorpoint Financial joint venture. License requirements include a minimum of HK$25 million in capital, 100% reserve backing, and redemption of stablecoins within one business day.
Analysts at Conventus Law called this move a strategic play for financial leadership, noting that Hong Kong aligned itself with Singapore, the UAE, and the EU as early leaders in controlled stablecoin environments.
Japan’s Push to Reclassify Crypto as a Financial Product
Japan’s Financial Services Agency finalized plans in late 2025 to reclassify 105 cryptocurrencies as financial products under the Financial Instruments and Exchange Act, or FIEA. If Japan’s Diet approves the amendments in 2026, crypto gains will shift from the current progressive tax system, which can reach as high as 55%, to a flat 20% rate that matches the tax on stock investments.
The FSA also plans to introduce insider trading rules and mandatory disclosure requirements for listed crypto assets. These changes would bring crypto oversight in line with how Japan already regulates its equity markets.
As of January 2025, Japan surpassed 12 million active crypto accounts, with holdings on domestic platforms exceeding 5 trillion yen, which is roughly 34 billion dollars. The reform push follows that adoption surge.
Singapore’s Tightening on Overseas Services
Singapore remains a leading institutional crypto hub, but the Monetary Authority of Singapore introduced tighter restrictions starting June 2025 on crypto firms serving overseas clients. A separate licensing regime for digital token service providers now grants access only in limited cases.
In September 2026, MAS put out a new consultation on stablecoin issuance rules. Proposals included joint issuance between Singapore and foreign issuers, recognition of select foreign-issued stablecoins, and an explicit ban on paying interest on stablecoins.
China’s Digital Yuan vs Private Crypto Ban
China has gone in the opposite direction from Hong Kong. A joint notice from the People’s Bank of China and seven other regulatory agencies in February 2026 reinforced the ban on unapproved RMB-pegged stablecoins. Bitcoin, Ethereum, USDT, and other private cryptocurrencies are not legal tender in China.
At the same time, China continues building out the digital yuan, also called e-CNY. It is the country’s central bank digital currency and the only government-sanctioned digital currency. According to the Wikipedia entry on the digital renminbi, e-CNY carries legal tender status domestically and is issued directly by the People’s Bank of China.
China is not stepping back from digital finance. It is channeling that activity entirely through state-controlled infrastructure.
What Are the Top FTAsiaEconomy Crypto Trends Right Now?
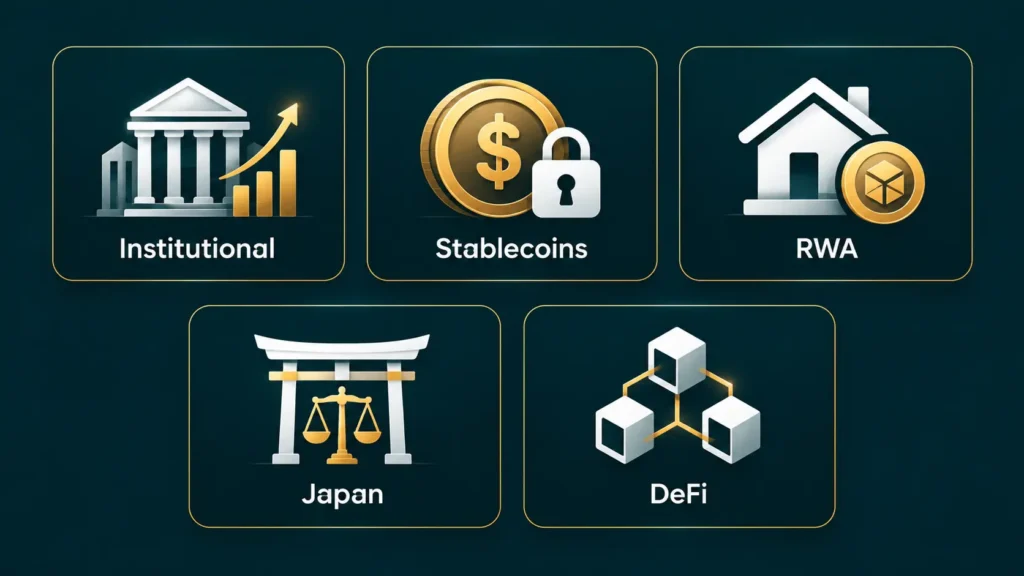
The biggest shift across Asian crypto markets is a move away from retail speculation toward institutional use. Five trends define that shift clearly.
Institutional adoption, stablecoin payment growth, real-world asset tokenization, Japan’s regulatory reform, and DeFi expansion in Southeast Asia are the five trends most worth watching across Asia’s crypto markets in 2025 and 2026.
Trend 1: Institutional Adoption Replacing Retail Speculation
Major banks in Asia are no longer watching crypto from the outside. Standard Chartered and DBS Bank in Singapore have launched digital asset custody and trading services. Sovereign wealth funds and major investment firms are allocating capital to blockchain projects.
Japan’s FSA data shows crypto holdings on domestic platforms crossed 34 billion dollars in early 2025. Chainalysis attributes much of Asia’s adoption acceleration to institutional participation, noting that India’s growth was boosted by both regulatory momentum and institutional entry.
Hong Kong’s licensing structure reinforces this shift. Licensed issuers must meet the same disclosure and custody standards used in traditional finance. That raises the floor for participation and filters out less serious operators.
Trend 2: Stablecoins as Payment Infrastructure, Not Speculation
Stablecoins are the fastest-growing category across Asian crypto markets, and the reason is practical: they settle faster and cost less than legacy payment systems.
As of September 2025, the global stablecoin market cap exceeded 300 billion dollars. Cross-border payment volume using stablecoin rails grew more than 1,000% in the first half of 2025, according to data shared by Bybit CEO Ben Zhou at the TOKEN2049 Singapore conference.
Asia trades more stablecoins by volume than any other region. USDT and USDC dominate the private market, primarily used for remittances, cross-border trade settlements, and payments rather than speculation. The Bank for International Settlements notes this pattern is strongest in markets where currency volatility is high and alternative banking access is limited.
Trend 3: Real-World Asset Tokenization
Real-world asset tokenization means converting physical assets, including real estate, government bonds, and commodities, into digital tokens that can be traded on a blockchain.
The global RWA market crossed 30 billion dollars in Q3 2025, up from 5 billion dollars in 2022. That represents more than 400% growth in three years, according to the Q3 2025 RWA Tokenization Market Report from InvesTax. Private credit accounts for roughly 17 billion dollars of that total, with tokenized US Treasuries making up much of the rest.
Asia is central to this growth. Hong Kong has seen pilots for tokenized commercial real estate and EV charging revenue rights. McKinsey and Standard Chartered project the total tokenized asset market could reach between 4 trillion and 30 trillion dollars within the coming decade.
The Oxford Law Blog published a research paper in December 2025 noting that as of September 2025, the global RWA market stood at 30.91 billion dollars and that Asia’s proactive regulatory approach, particularly in Hong Kong and Singapore, has made the region a focal point for tokenization activity.
Trend 4: Japan’s Regulatory Reform and the ETF Window
Japan’s planned FIEA reclassification is not just a tax story. If passed, it clears the path for spot crypto ETFs in Japan, including Bitcoin and Ethereum products. That would put Japan in line with moves already made in the US, Hong Kong, and the UAE.
Japan Exchange Group, which runs the Tokyo Stock Exchange, is separately reviewing how listed companies handle large crypto positions. Three listed firms paused plans to accumulate tokens in late 2025 after warnings that large digital asset holdings could restrict their ability to raise capital.
The FSA is aligning disclosures, conduct rules, and tax treatment with traditional finance standards. For institutional investors and global crypto firms, Japan looks more open to regulated trading, but less willing to allow equity strategies built around speculative token accumulation.
Trend 5: DeFi and Web3 Growth in Southeast Asia
Decentralized finance is growing fastest where traditional banking is least accessible.
Vietnam, the Philippines, and Indonesia are among the top global markets for grassroots DeFi activity. According to Chainalysis, nearly 20% of the Philippines’ crypto-related web traffic goes to gaming and blockchain-based applications. Platforms including PancakeSwap, Aave, and dYdX have strong user bases across Southeast Asia.
This is financial access, not speculation. People are using decentralized platforms to borrow, lend, and earn without needing a bank account. Web3 tools and NFT-based gaming also drive activity in these markets, where cultural adoption through entertainment often moves faster than regulatory frameworks.
For businesses operating in the fintech and crypto space, communicating with this audience through well-structured digital outreach matters. AI-powered email tools like those at FreeMail AI’s AI mail generator help fintech teams build targeted campaigns without manual overhead.
What Are the Risks and Open Questions in Asia’s Crypto Market?
The biggest structural risk is regulatory fragmentation. Hong Kong’s licensing model and China’s enforcement model sit at completely opposite ends of the spectrum, and that gap is not closing. A business operating across multiple Asian markets cannot use one compliance playbook. Country-by-country strategy is standard practice, not the exception.
Market volatility is a second factor. Research and market commentary describe Asia’s crypto markets as resilient through price swings, but neither Chainalysis’s 2025 report nor the country-specific regulatory sources reviewed here provided region-specific volatility data. That absence is worth naming rather than filling with a guess.
Some important details remain unresolved. India’s specific retail investor guidance is still developing. South Korea’s stablecoin framework is in early planning stages. Individual tax treatment across most Southeast Asian countries is not clearly documented in publicly available sources as of October 2026.
A well-researched article acknowledges these gaps rather than projecting certainty where none exists.
Frequently Asked Questions About FTAsiaEconomy Crypto Trends
Which Asian country leads crypto adoption?
India ranked number one in Chainalysis’s 2025 Global Crypto Adoption Index for the second year in a row. Singapore ranked number one in adoption penetration rate, with ownership as high as 24.4% in 2025 surveys. Asia-Pacific overall grew 69% in on-chain transaction volume in the 12 months to June 2025, from 1.4 trillion dollars to 2.36 trillion dollars.
What is Hong Kong’s stablecoin regulation?
Hong Kong passed the Stablecoins Ordinance on May 21, 2025. It took effect on August 1, 2025. The law requires fiat-referenced stablecoin issuers operating in or from Hong Kong to obtain a license from the HKMA. In April 2026, HKMA granted its first two licenses to HSBC and to Anchorpoint Financial, the Standard Chartered-led joint venture.
Is crypto legal in Japan?
Yes. Japan recognized cryptocurrency as a legal payment method in 2017. Japan’s FSA is now working to reclassify digital assets as financial products under the FIEA. If the amendments pass in 2026, the maximum tax on crypto gains drops from 55% to a flat 20%, aligning crypto with stock investment taxes. Spot Bitcoin and Ethereum ETFs could also follow.
What is RWA tokenization and why does it matter in Asia?
Real-world asset tokenization converts physical assets into blockchain-based digital tokens. The global RWA market crossed 30 billion dollars in Q3 2025, up from 5 billion dollars in 2022. Asia is central to this growth. Hong Kong and Singapore are leading pilot programs for tokenized real estate, bonds, and money market funds. McKinsey and Standard Chartered forecast the market could reach between 4 trillion and 30 trillion dollars in the coming decade.
Is crypto banned in China?
China bans private cryptocurrencies and unapproved stablecoins as legal tender. Bitcoin, Ethereum, and USDT are not recognized as legitimate currencies. At the same time, China is actively expanding the digital yuan, or e-CNY, which is its central bank digital currency and the only state-sanctioned digital currency in the country. Blockchain technology for infrastructure purposes remains encouraged by the government.
What is the difference between a stablecoin and a CBDC?
A stablecoin is a privately issued digital currency pegged to a fiat currency, like USDT or USDC. A CBDC is issued directly by a central bank, like China’s e-CNY. In Asia, both are growing but in different parts of the financial system. CBDCs are government-controlled and legally recognized. Stablecoins are privately issued, regulated through licensing regimes, and used primarily in private markets for payments, remittances, and trading.
Building Communication Tools That Keep Up With a Fast-Moving Market
The crypto and fintech sectors in Asia are moving fast. Regulatory updates land monthly. New licensing requirements change who can operate where. Businesses that serve these markets need communication tools that can keep pace.
FreeMail AI offers an AI-powered email campaign generator that helps fintech teams, crypto startups, and financial services businesses build targeted email campaigns without manual setup. Automated outreach, personalized templates, and real-time analytics are built into one platform designed for businesses that do not have time for slow communication workflows.